Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Learn how supply overhang can pressure crypto prices.
In crypto, supply overhang is a known or expected pool of tokens or coins that could become sellable and pressure price.
You will usually see the phrase around token unlocks, low-float launches, treasury wallets, escrow releases, government selling, or old holders waiting to exit near break even. That does not make every overhang a disaster. It means you should ask a simple question: can demand, liquidity, and holder incentives absorb the supply waiting nearby?
Supply overhang in crypto means a known or likely pool of tokens or coins could hit the market and create selling pressure. In general finance, market overhang describes supply waiting to be sold, or sellers large enough to make buyers cautious. Crypto adds token schedules, on-chain wallets, vesting cliffs, and thin exchange liquidity to the same basic idea.
The overhang can be future supply or existing supply. A locked investor allocation can become transferable next month. A foundation wallet can distribute or sell over time. A bankruptcy estate, government wallet, miner, validator, or whale can become a visible seller. A crowd of underwater holders can also wait above the current price, ready to sell once they finally reach break even.
The phrase gets sloppy on social feeds, so keep the boundary clear:
That third case surprises many users. Supply overhang does not always mean new tokens are being created. Sometimes the supply already exists, but holders have a reason to sell into strength.
The chart may rally, then stall near the price where earlier buyers want out. Supply overhang is not a single metric. It is the pressure that appears when sellable supply, seller incentives, and weak absorption arrive together. That setup is rarely calm.
Supply overhang pressures crypto prices because buyers must absorb the supply that sellers want to move. If demand is deep enough, the market may digest the overhang quietly. If demand is weak, even a well-known supply event can push price lower or cap a rally.
Think about two tokens with the same unlock date. One trades with deep liquidity, broad demand, and gradual releases. The other trades in a thin book, with a large cliff unlock going to early investors. The calendar date looks similar. The price risk does not.
Pressure usually grows when several signals line up:
The mechanism is plain supply and demand. Crypto makes it sharper. Many tokens have small public floats, aggressive incentives, and holder groups with very different cost bases. If early holders are far in profit and public buyers are thin, supply overhang can turn into exit liquidity risk.
But supply overhang is a headwind, not a remote control. It does not automatically force a red candle. Markets can sell off before the event, absorb supply on the day, or ignore it until liquidity disappears later. The useful question is more grounded: who can sell, when can they sell, how much can they sell, and can the market take it?
The main types of supply overhang are future issuance, known seller supply, and overhead holder supply. They can overlap, but they are different risks. Blending them together is how a simple tokenomics check becomes chart soup.
Each type asks a different question:
Use the categories below to keep the diagnosis clean before jumping to a trade decision.
| Type Of Supply Overhang | What To Check |
|---|---|
| Future Issuance | Vesting dates, cliff size, linear release pace, recipient groups, and whether tokens become transferable or only claimable |
| Known Sellers | Treasury wallets, escrow rules, foundation plans, whale concentration, estate distributions, and market-maker inventory |
| Overhead Holders | Prior trading zones, holder cost basis, failed breakouts, and whether rallies keep meeting sell walls |
| Emission Pressure | Mining rewards, staking rewards, incentive programs, and whether new rewards are sold to cover costs |
| Stacked Overhang | Whether several supply sources arrive while liquidity and demand are already weakening |
Future issuance is the version most crypto users know. It includes team, investor, treasury, incentive, staking, mining, or reward supply that has not fully entered the tradable market. A cliff unlock can create a sudden test. Linear vesting can create a slower drip that still matters if demand stays weak.
Known seller supply is about identifiable holders. A treasury, foundation, escrow, market maker, government wallet, bankruptcy estate, or large whale may already control tokens or coins. Overhead holder supply comes from old buyers. If many holders bought higher and waited through a drawdown, bagholder zones can cap moves even when no fresh token unlock exists.
The table is a filter, not a verdict. A large treasury can be harmless if it is locked, transparent, and used slowly. A small unlock can be ugly if the token trades in a shallow market and recipients are likely sellers.
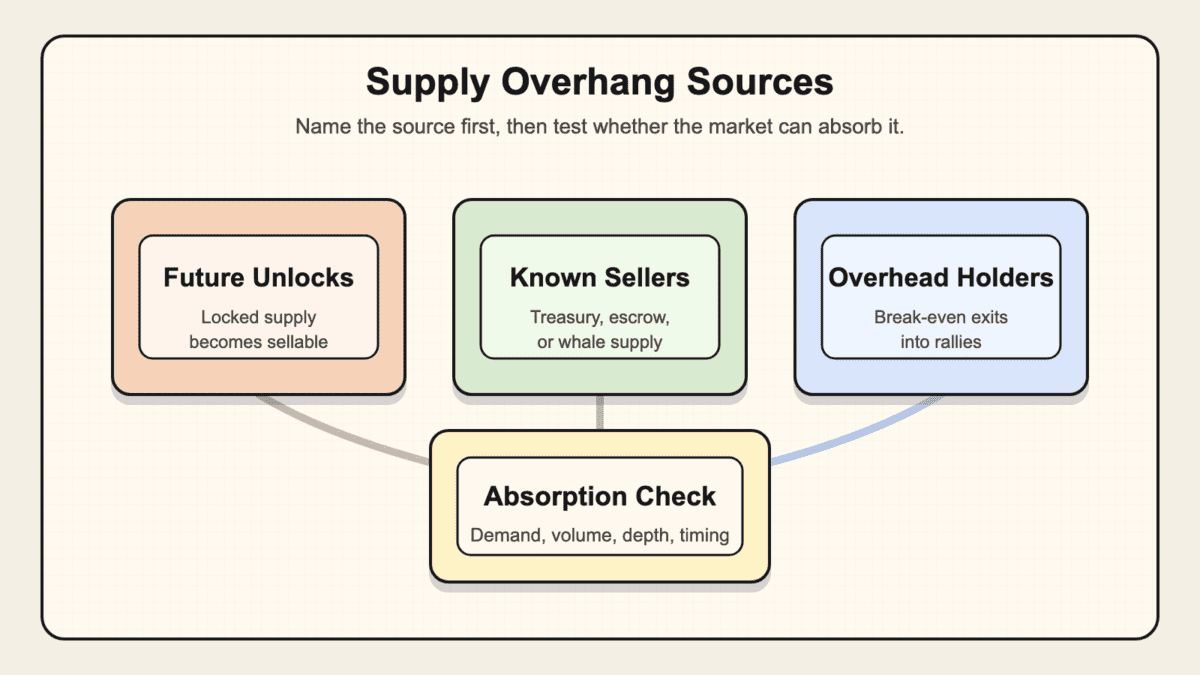
The useful move is to name the type first. Then compare it with liquidity, demand, and seller incentives. Otherwise every overhang becomes the same vague warning. Vague warnings are where bad trades start.
You spot supply overhang before buying a token by comparing future sellable supply with current liquidity and demand. Start with supply structure, then move to market absorption. A token’s price per coin is one of the weakest shortcuts in this process.
Low unit price tells you almost nothing. A token at $0.03 can be expensive if the FDV is huge and most supply is still locked. A token at $300 can be cleaner if most supply already trades, liquidity is deep, and no major seller group is waiting nearby.
Before buying, run the checks in order. The goal is to move from supply math to actual market absorption:
The recipient group deserves extra attention. Team, investor, grant, treasury, community reward, staking, and market-maker allocations can behave differently. Early investors may have profit and a mandate to return capital. User incentives may create drip selling. Treasury tokens may fund operations rather than hit the market at once.
Volume also needs a sanity check. Headline daily volume can include wash-like churn, internal exchange activity, or low-quality trading. Order-book depth and slippage often tell you more. If a modest sell order would move price hard, the market may not absorb a large overhang without pain.
Two shortcuts cause the most damage:
After that, define your own reason for holding. A real thesis can survive a known overhang if the size, timeline, and demand case are clear. That is closer to a hold with conviction than a hope trade. Hope trades usually sound brave right before they become accounting lessons.
The final check is source quality. Token dashboards, project docs, governance posts, exchange notices, and on-chain wallets can disagree. When they do, write down the uncertainty. “Unknown” is a better input than a confident spreadsheet built from stale data.
Supply overhang differs from FDV, circulating supply, and token unlocks because it describes market pressure, not just a supply number. FDV estimates valuation under a broader supply base. Circulating supply counts what data providers treat as live now. A token unlock is an event. Supply overhang is the pressure those details can create once sellable supply meets the market.
That distinction prevents two common mistakes. First, high FDV does not prove an immediate selloff. Second, a healthy circulating market cap does not prove future supply is harmless. The danger sits in the gap between what trades today and what can become sellable later.
Use each metric for the job it can actually do.
| Metric | What It Does And Does Not Prove |
|---|---|
| Circulating Supply | Shows supply counted as live now, but not every future release or seller incentive |
| Total Supply | Shows created tokens, but not whether they are liquid, locked, burned, or likely to sell |
| Max Supply | Shows an upper cap where one exists, but not timing or current market pressure |
| Unlocked Supply | Helps estimate movable supply, but methodologies vary across data providers |
| Market Cap | Values current circulating supply, but can understate future dilution risk |
| Fully Diluted Valuation | Applies current price to a broader supply base, but it is not a price forecast |
| Market Cap To FDV Ratio | Highlights how much valuation sits outside float, but says little about buyer demand |
| Unlock Size Versus Volume | Tests absorption risk, but headline volume can be lower quality than it looks |
CoinGecko Research reported in its updated low-float study that 21.3% of the top 300 crypto assets by market cap were low-float, using a market-cap-to-FDV ratio below 0.5. That data point shows the risk is not tucked away in some fringe corner of crypto.
Still, FDV is a signal, not a sentence. A low-float token with clear releases, strong demand, and deep liquidity may handle dilution better than expected. A token with a nicer ratio can still face supply overhang if a large seller or underwater holder zone waits nearby.
Supply overhang is not automatically bearish when the market can absorb the supply, already expected the event, or has stronger demand than sellers. The risk can be real without producing an immediate dump. Crypto loves simple rules. Markets keep ruining them.
Known events often move before the date. Traders may sell early, hedge exposure, or short the token ahead of an unlock. If price already fell into the event, the actual release can look calm. Sometimes the lack of a fresh collapse attracts buyers who waited for confirmation.
Several setups can reduce the pressure:
Demand flow is the core variable here. During a strong market rotation, capital can move into a sector fast enough to absorb supply that would look scary in a dead market. A token with real narrative demand can also trade better than its unlock calendar suggests, at least while the story keeps pulling buyers.
But “priced in” is not a magic eraser. A known overhang can still bite if recipients sell harder than expected, liquidity thins, demand fades, or a broader market selloff arrives at the same time. No dump today means the market passed one absorption test. It does not mean dilution vanished forever. Keep the takeaway balanced: check the size, timing, recipients, liquidity, and demand before treating any unlock as either doom or a nothing burger.
Traders and long-term investors should use supply overhang differently. Traders care about timing, liquidity, positioning, and invalidation. Longer-term investors care about dilution, entry price, position size, and whether the token can grow through future supply.
For traders, the event path matters. A token can sell off before an unlock, bounce after the unlock, then fade again if recipients start distributing later. The calendar date is only one part of the trade. The market’s reaction afterward often tells you more.
Traders can make the risk more concrete:
That last point is where supply overhang can overlap with a crowded top signal. If everyone is celebrating while a large seller group is about to become liquid, the party may still continue, but at least check the exits before dancing near them.
Longer-term investors have a different job. They do not need to trade every unlock. They need to decide whether the token structure supports patient ownership. A project can have good technology, real users, and still a token that keeps handing cheap supply to sellers.
Longer-term checks are simpler, but not easier:
For a longer hold, ask whether the token can earn its future supply. That means stronger usage, clearer cash flows or utility, better distribution, and enough liquidity to survive releases. It also means sizing the position so one messy unlock does not force an emotional decision.
Both groups should verify the schedule from primary project materials or reliable trackers. Social screenshots can flag a concern. They are not enough for sizing a trade or a long-term position.
Start supply overhang research by identifying which kind of supply could become sellable. A token unlock, a treasury wallet, a whale, a miner, or an overhead holder zone each creates a different question. Name the source before judging the risk.
Then compare the source with market absorption. Size by itself is incomplete. A large release into deep demand can pass. A smaller release into thin liquidity can sting. The market does not care how tidy the spreadsheet looked.
Use this short workflow before buying, holding, or trimming:
Keep the conclusion humble. Supply overhang is a warning system, not a price prediction. It tells you where selling pressure may come from, what data to check, and what could invalidate the bullish story.
The best use is practical. If the overhang is small, transparent, and absorbed, you may simply monitor it. If it is large, concentrated, and paired with weak demand, you have a reason to wait, size down, or skip the trade. Missing one bad setup is rarely expensive. Buying the one everyone warned you about can be.
After the first pass, write down what would change your view. Maybe a large unlock gets relocked. Maybe the treasury publishes a clear spending schedule. Maybe price holds only because volume vanished. Those are different signals, and they deserve different decisions.
That last step is where discipline beats cleverness. You do not need a perfect supply model to avoid the obvious traps. You need enough context to know when the risk is normal, when it is overstated, and when the market is asking you to be someone else’s liquidity.
Supply overhang in crypto is a known or expected pool of tokens or coins that could become sellable and pressure price. It can come from token unlocks, treasury wallets, escrow releases, large holders, miner rewards, or underwater holders waiting to exit near break even.
The term is useful because it turns a vague fear into a checklist. Ask who can sell, when they can sell, how much supply is involved, and whether market demand can absorb it.
Supply overhang is a risk for crypto, but it is not automatically bad in every case. It becomes more dangerous when sellable supply is large, recipients are likely sellers, liquidity is thin, and demand is weak.
It can matter less when releases are gradual, transparent, already expected, or absorbed by strong buying. The key is context. A clean supply schedule is very different from surprise selling into a shallow market.
Supply overhang does not always make a token dump. Markets can price in known supply, sell off before the event, absorb the release, or even rally after uncertainty clears.
The danger is assuming that a calm unlock means the risk disappeared. Supply can still pressure price later if recipients sell slowly, demand fades, or liquidity dries up after the initial event.
Token unlocks create supply overhang when previously locked allocations become transferable, claimable, or easier to sell. The overhang is stronger when the unlock is large compared with current float, normal volume, and visible order-book depth.
Recipient incentives matter too. Early investors, team members, grant recipients, market makers, and community reward users may behave differently. The unlock date is only the starting point.
Supply overhang is the market pressure that can come from sellable supply, while FDV is a valuation metric. FDV applies the current token price to a broader supply base, often total or max supply.
FDV can warn you that future dilution may be large, but it does not prove sellers will appear tomorrow. Supply overhang adds timing, liquidity, holder incentives, and demand to the analysis.
Bitcoin can have supply overhang, even though it does not have token unlocks like many altcoins. The overhang can come from miners selling rewards, large holders distributing coins, government wallets, estate sales, or old holders selling near prior cost-basis zones.
That kind of overhang is usually about known sellers or overhead holder supply. It is different from a vesting schedule, but the market still has to absorb the coins.