Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Physical Address
304 North Cardinal St.
Dorchester Center, MA 02124
Synthetic exposure meaning, ownership gaps, and risks.
Synthetic exposure means getting the economic effect of an asset’s price movement without directly owning that asset.
In crypto, that gap can be useful or dangerous. A product may track Bitcoin, a stock, a dollar, or an index while giving you none of the custody, voting rights, redemption rights, dividends, or legal claims that direct ownership would normally suggest.
That is why the phrase shows up around perps, synthetic assets, tokenized stocks, ETFs, ETPs, synthetic dollars, and RWA products. The label is not the answer. The structure underneath is.
Synthetic exposure in crypto is a position that gives you price exposure to an asset without putting that asset directly in your wallet or account. You may gain when the reference asset rises, lose when it falls, or take the opposite side through a short position.
The simple example is a Bitcoin perpetual future. A long BTC perp can rise and fall with Bitcoin’s price, but you do not own BTC. You own a derivative position that depends on margin, funding, exchange rules, and liquidation mechanics.
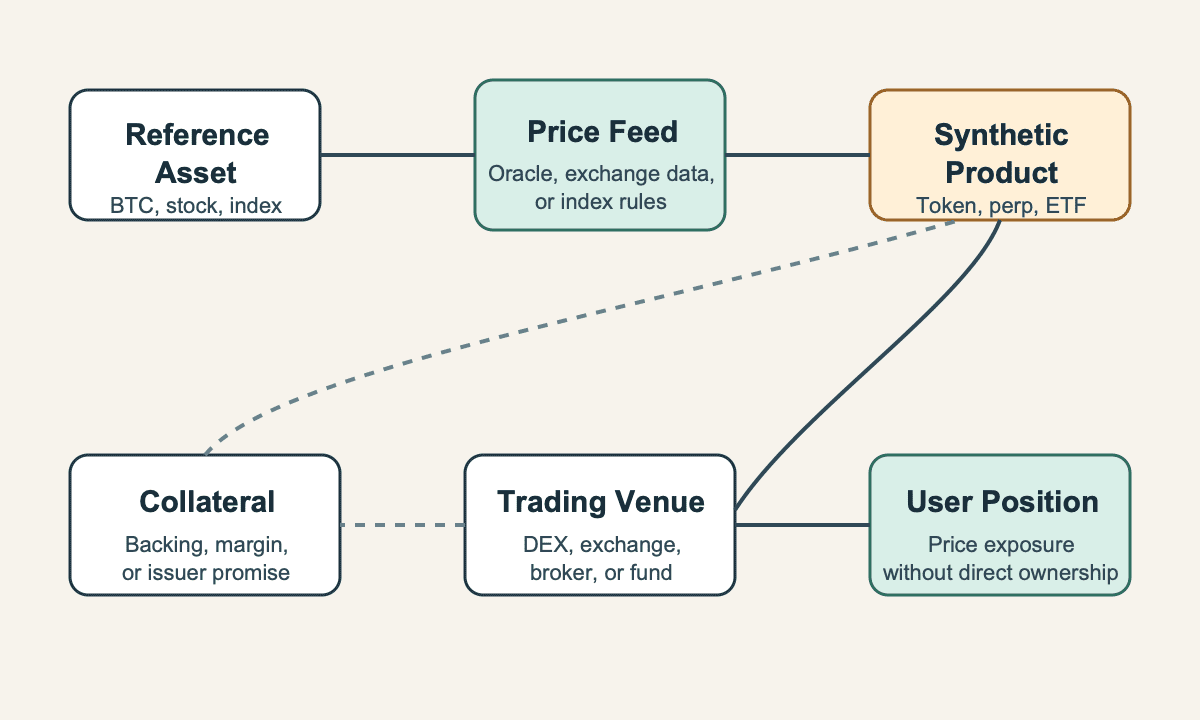
The same idea can appear in a token, fund, broker wrapper, structured product, or DeFi protocol. The asset being tracked is the reference asset. The thing you hold is the synthetic product or position.
Keep three pieces separate before you trust the label:
Keep that split clear. Synthetic exposure can copy price without copying custody, redemption, voting rights, dividends, transfer rules, or legal claims.
So the synthetic exposure meaning is not “fake asset.” It is constructed exposure. Sometimes that construction is transparent and useful. Sometimes it is a fog machine with a ticker.
The right question is not only, “Does it track the price?” Ask what you actually receive, who controls the backing, and what happens under stress. Clear answers make a product easier to assess. Evasive answers mean you are carrying risks the product has not named.
Synthetic exposure works by connecting a product or position to a reference asset. The connection can come from derivatives, collateral, smart contracts, issuer promises, fund rules, or a trading venue that prices the position against the asset.
In DeFi, a synthetic token might depend on collateral and an oracle that reports the reference price. In perps, the exposure comes from a contract whose value tracks an index price. In ETFs or ETPs, the wrapper may hold assets directly, use futures, or use another structure that creates the desired price path.
The moving parts are easier to inspect when you break them down:
| Part Of The Structure | Question To Ask |
|---|---|
| Reference asset | What asset, index, stock, commodity, or crypto price is being tracked? |
| Tracking method | Is the exposure created through spot backing, derivatives, token rules, or issuer promises? |
| Backing or collateral | What supports the position if the market moves hard? |
| Price feed | Which oracle, exchange index, or pricing source decides the value? |
| Exit path | Can you redeem, close, sell, or only hope another buyer appears? |
Stress behavior is the part beginners often miss. A synthetic token may look clean on a quiet chart, then wobble when collateral falls, an oracle lags, liquidity thins, or redemptions pause.
Perps add another layer. Funding payments can make a long or short expensive over time. Liquidation rules can close the trade before the reference asset reaches the price you had in mind.
So a synthetic exposure product is only as clear as its weakest moving part. If you cannot identify the reference asset, tracking method, backing, price source, venue, and exit route, you do not understand the position yet.
Synthetic exposure is not the same as owning the underlying asset. Ownership asks who controls the asset and what rights come with it. Exposure asks whether your profit and loss tracks the asset’s price.
Ownership and exposure can overlap, but they do not have to. Holding BTC in self-custody is direct asset control. Holding a BTC perp is price exposure. Buying a tokenized stock may give a legal claim, a broker-like entitlement, or only synthetic tracking, depending on the product.
Start with the wrapper before you compare the chart:
| Product Wrapper | What To Verify Before Trusting The Exposure |
|---|---|
| Spot crypto in self-custody | You control the keys, but you also handle wallet security and recovery. |
| Exchange spot balance | You have account-based exposure, but withdrawals and custody depend on the venue. |
| Spot ETF or ETP | You get a regulated wrapper, not onchain custody in your own wallet. |
| Futures-based or synthetic ETP | Tracking may depend on futures, swaps, counterparties, fees, or roll costs. |
| Wrapped asset | The token works on another chain, but bridge or custodian risk enters. |
| Tokenized RWA | Rights, transfer limits, redemption, and jurisdiction can vary by issuer. |
| Synthetic token or perp | You get price movement, but not ownership of the reference asset. |
This is why self-custody users talk so much about keys. With self-custody wallets, the point is direct control of crypto assets. With synthetic exposure, the point is usually market access or trading behavior.
Neither structure is automatically better. They solve different problems and carry different failure modes.
The dangerous mistake is buying price exposure while assuming ownership rights. A synthetic stock token may move like a stock, but that does not mean you receive shareholder voting rights or dividends. A synthetic dollar may trade near $1, but that does not mean it has bank reserves behind every token.
Possession can also matter for tax, legal, accounting, or religious-compliance analysis. This guide is not professional advice. It only flags the first question: do you own the asset, or only track it?
Synthetic exposure shows up wherever crypto users want price movement without direct ownership. That includes DeFi synths, perpetual futures, tokenized-stock lookalikes, synthetic dollars, options-like structures, futures-based funds, and some RWA-adjacent products.
DeFi synths are the cleanest example. A protocol can let users mint or trade a token that tracks another asset. The token may depend on collateral, liquidations, and oracle pricing rather than a custodian holding the reference asset.
Perpetual futures are another everyday example. A long ETH perp gives synthetic long exposure to ETH. A short perp gives the opposite exposure. The trader uses margin, pays or receives funding, and faces liquidation if the position moves too far against them.
Tokenized stocks and RWAs are messier because labels can hide legal differences. A current Investor.gov page breaks tokenized securities into three models: issuer-sponsored, custodial, and synthetic. That is a useful reminder that a token can track a security without giving the same claims as owning that security.
Synthetic dollars sit in another bucket. Some are built to track USD through collateral, hedges, or market positions instead of simple bank-reserve backing. The user sees dollar behavior, but the engine underneath may be much more exposed to crypto market conditions.
ETFs and ETPs need the same careful reading. Some hold the asset directly. Some use futures or other instruments. Some use synthetic structures. The wrapper name alone does not tell you the tracking method.
So the recurring lesson is simple: “synthetic exposure crypto” is not one product. It is a pattern that can appear inside many wrappers, and each wrapper changes what can break.
Traders use synthetic exposure because direct ownership is not always the fastest or most useful route. Sometimes the goal is fast price exposure, short exposure, leverage, hedging, or access to an asset that is hard to hold directly.
A trader may use a perp to short Bitcoin without borrowing BTC. A fund may use futures inside an account wrapper. A DeFi user may want exposure to a stock, commodity, or dollar price without leaving onchain rails.
The valid use cases are real:
But useful does not mean safer. Synthetic exposure often adds more moving parts than direct ownership. Those parts can add cost, forced exits, counterparty risk, or surprising behavior under stress.
Capital efficiency is the classic tradeoff. You may post less collateral than a full spot purchase would require. That frees capital, but it also means the position can be liquidated.
Access has a similar tradeoff. A product may offer exposure to a stock, commodity, private-company narrative, or foreign market. That access may come without the rights, protections, or redemption path you would expect from the underlying asset.
Synthetic exposure is best used when the user understands why the wrapper exists. If the reason is only “because it is easier to click,” the click may be doing too much work.
Synthetic exposure can affect crypto markets through liquidity, hedging, funding rates, leverage, and price discovery. It does not require every trade to touch the underlying asset directly.
Perp markets show this clearly. A large wave of leveraged longs can change funding rates and make the long side expensive. If price moves against those longs, liquidations can add forced selling pressure.
Market makers and dealers may also hedge synthetic exposure in spot or futures markets. That hedging can connect wrapper demand to the underlying asset, even when users never take custody themselves.
This is where “paper Bitcoin” anxiety comes from. Spot holders see huge derivative volumes and worry that synthetic claims can overwhelm actual asset demand.
That concern deserves a grown-up answer. Synthetic exposure can influence short-term liquidity and price discovery. But claims about suppression, fake supply, or coordinated manipulation need market data, not vibes with a chart and a dramatic thread title.
Thin markets can make the effect sharper. In a PvP market, exits can feel adversarial because one trader’s clean exit may be another trader’s loss. Add leverage and the room gets smaller fast.
For traders, the point is simple. If a market is dominated by derivatives, funding, and thin liquidity, price can move violently without much spot activity. That does not prove manipulation. It does mean you should understand the venue before assuming the chart reflects calm organic demand.
The main risks of synthetic exposure come from the structure between you and the reference asset. Each extra layer can create a failure point, cost, or right that does not exist.
Start with backing. If a synthetic product depends on collateral, you need to know what the collateral is, where it sits, and what happens when its value drops. If it depends on an issuer or counterparty, you need to know what that party owes you.
Then look at the market rails:
Liquidity deserves its own warning. A synthetic product can look active when the narrative is hot, then become awkward when buyers disappear. That is when exit liquidity stops being a meme and starts being the whole trade.
Leverage also changes the risk shape. A 10% move in the reference asset may not just create a 10% loss. It may trigger margin calls, liquidation, wider spreads, or forced deleveraging across the venue.
Rights mismatch is quieter but just as important. A product can track a stock price without giving shareholder rights. It can track a commodity without giving delivery. It can track BTC without letting you withdraw BTC.
The boring checks are the useful ones. Read the redemption terms. Check spreads. Look at depth. Find the oracle source. Understand liquidation. If the answers are vague, the risk is not vague. It is just being handed to you with better lighting.
Check a synthetic exposure product by asking what backs it, what rights you get, how prices are tracked, where liquidity comes from, and how you exit. If those answers are not clear, the product is too foggy for a beginner.
Do this before thinking about yield, upside, or convenience. The cleanest marketing page in the world cannot rescue a structure you cannot explain.
Use this checklist:
| Check | What A Clear Answer Looks Like |
|---|---|
| Reference asset | The product names the exact asset, index, or market it tracks. |
| Backing | Collateral, issuer obligation, derivative position, or fund structure is visible. |
| User rights | Ownership, redemption, voting, dividends, and claims are plainly described. |
| Price source | The oracle, index, exchange feed, or calculation method is identified. |
| Liquidity | Depth, spreads, venue quality, and withdrawal or redemption limits are inspectable. |
| Leverage | Margin rules, funding, liquidation levels, and forced-close mechanics are clear. |
| Costs | Fees, funding, roll costs, spreads, and borrowing costs are not hidden. |
| Stress case | The product explains trading pauses, oracle failures, redemptions, and insolvency paths. |
Position size comes after those answers, not before. If the product has leverage, weak exits, or unknown backing, sizing it like a spot holding is a mistake. The same logic that makes going full port risky in a token can be even nastier in a synthetic wrapper.
Now check the human layer. Who can change the rules? Is there a multisig, issuer, broker, governance vote, fund board, or exchange risk engine involved? Can that party pause trading, adjust margin, block jurisdictions, or change redemption terms?
Also check whether the product is meant for minutes, months, or years. Perps can be useful for short trades but expensive to hold if funding turns against you. A fund wrapper may be fine for account access but poor for onchain settlement. A synthetic token may be useful in DeFi but fragile when liquidity dries up.
The best products make these tradeoffs boringly clear. The worst ones hide them behind a chart that mostly tracks the thing you wanted.
Synthetic exposure may make sense when you want a specific payoff and understand the wrapper. It is a tool, not a purity test.
For traders, the strongest cases are hedging, short exposure, and short-term directional trades. A perp can hedge a spot position. An options-style construction can shape upside and downside. A synthetic token can create exposure that would be hard to hold directly onchain.
For investors, the valid cases are narrower but still real:
Institutions may use synthetic exposure because policies allow certain wrappers but not direct custody. DeFi users may use it because the asset plugs into lending, liquidity, or collateral systems.
Those reasons can be rational. The mistake is turning a convenience tool into a substitute for due diligence.
The holding period should also match the wrapper. A short hedge can tolerate costs that would slowly chew through a long-term position. A DeFi position may be useful while liquidity is deep, then become awkward when incentives fade.
So ask it plainly: does this wrapper solve the exact problem you have? If the answer is only “it gives me exposure,” the product has not earned much trust yet.
The clean standard is this: synthetic exposure may fit when you want price behavior and do not need ownership rights. If you need custody, redemption, voting, dividends, or direct possession, a synthetic product may be the wrong instrument.
Avoid synthetic exposure when the product cannot explain its backing, rights, pricing, liquidity, leverage, and exit route. A vague structure is not beginner-friendly just because the chart looks familiar.
Be especially careful when the marketing language makes price tracking sound like ownership. “Exposure to Tesla” is not the same as owning Tesla shares. “BTC exposure” is not the same as withdrawing BTC to your own wallet.
The warning signs are usually plain:
None of that automatically makes a product a scam. A complex product can be legitimate. But complexity without clear answers is not sophistication. It is a smoke machine with a fee schedule.
Beginners should also avoid synthetic exposure when they actually want long-term asset ownership. If the goal is to hold ETH for years, a synthetic ETH position with funding costs and liquidation risk is solving a different problem.
The same goes for products that rely on hot narratives. Tokenized private-company exposure, synthetic commodities, and cross-asset perps can be useful for traders. They can also turn into cramped exits when attention leaves.
Synthetic exposure sits near several crypto terms, but the borders matter. A synthetic asset is a token or position designed to mirror another asset’s value. A derivative in crypto is a contract whose value comes from another asset, which makes it the broader category behind many synthetic positions.
Perps are the trading example most crypto users meet first. Perpetual futures explain funding, margin, and liquidation in the wrapper where synthetic long and short exposure usually shows up.
Wrapped assets are different. A wrapped BTC token on another chain may be backed by BTC held elsewhere, which creates bridge or custodian risk. It is not automatically synthetic exposure, because the token may represent a claim on the wrapped asset rather than pure price tracking.
RWAs are also different. A tokenized real-world asset may represent a legal claim, a fund interest, a debt instrument, or something much thinner. You have to read the structure before deciding whether it is ownership, entitlement, or synthetic tracking.
Collateral, oracles, and liquidity connect all these concepts. Collateral supports the product. Oracles or price feeds help track the reference asset. Liquidity decides whether your screen price survives contact with your exit order.
Use that map before you trust the label. Trace the asset, the claim, the price source, and the exit path.
No. Synthetic exposure can track a crypto asset’s price without giving you direct ownership of that asset. Owning crypto usually means you can hold or withdraw the token. Synthetic exposure usually means you hold a derivative, token, fund share, or account position that follows the price.
In trading, synthetic exposure means creating the payoff of an asset or position through another instrument. A trader might use perps, options, futures, swaps, or structured tokens to gain long or short exposure without buying or borrowing the asset directly.
It depends on the ETF or ETP structure. A spot Bitcoin fund may hold BTC through custodians, while a futures-based or synthetic wrapper may use derivatives to track Bitcoin price. The wrapper name is not enough. Check the holdings, strategy, fees, and redemption rules.
Some tokenized stocks may be synthetic exposure, while others may represent a legal claim or entitlement. The key question is whether the token gives rights tied to the underlying security or only price movement. Voting, dividends, transfer limits, and redemption terms matter.
The biggest DeFi risk is usually a stack of risks, not one neat item. Collateral, oracles, smart contracts, liquidity, liquidation rules, and governance can all affect whether the exposure tracks properly and whether users can exit during stress.
Users choose synthetic exposure for hedging, short exposure, leverage, account access, DeFi use, or assets that are hard to hold directly. That can be useful when the structure is clear. It becomes dangerous when the user expects ownership rights that the product never offered.
Start with the reference asset, then work outward. If you cannot name the asset being tracked, the backing, the rights, the price source, and the exit route, do not trade the product yet.
The order matters. Price tracking tells you what the product is trying to copy. Backing and rights tell you what supports your claim. Liquidity and exits tell you whether the number on the screen can become money in your account.
The next steps are simple enough to keep on a sticky note:
For a perp, that means checking margin rules before the trade, not after the alert sounds. For a tokenized stock or RWA, it means reading the rights and redemption terms before assuming the ticker gives you the same claim as the underlying asset.
Then size the position as if the exit may get worse when you need it. That sounds gloomy, but it is the whole point of risk checks. Easy exits are abundant until everyone wants one.
Synthetic exposure can be a useful shortcut. Just do not confuse the shortcut with the destination. If you need ownership, custody, redemption, or legal rights, make the product prove it before your money does.